

Table of Contents
- Why Standard Payment Processors Fail Home Service Businesses
- What to Look for in a Payment Processor for Your Trade
- Mobile Credit Card Processing for Contractors in the Field
- Recurring Billing Software for Home Services and Maintenance Plans
- PCI Compliance for Mobile Payments: What Technicians Need to Know
- Hidden Fees and How to Audit Your Current Statement
- Hardware Troubleshooting and Connectivity on the Job Site
- Conclusion: Build a Payment Stack That Scales With Your Crew
- Frequently Asked Questions
Last Updated: September 8, 2026
Why Standard Payment Processors Fail Home Service Businesses
Standard payment processors are built for retail storefronts, not for crews working out of vans and trucks. The mismatch shows up fast: invoices that need emailing from a driveway, deposits collected before a job starts, and recurring billing for maintenance plans that a countertop terminal was never designed to handle. Payment processing for home service businesses demands a different set of tools, yet most providers sell the same one-size-fits-all package they offer a boutique clothing shop.
The structural problem is that home services run on irregular cash flow. An HVAC company might collect $12,000 in June and $3,000 in February, which makes predictable merchant account underwriting difficult (census.gov). Standard processors often respond by holding reserves or freezing funds during slow seasons, leaving contractors unable to pay suppliers.
The other failure point is the sales model itself. Many processors quote a low “qualified rate” and then layer on monthly fees, gateway charges, and PCI compliance costs that double the effective rate. For a contractor running 40 transactions a week, those hidden line items quietly erase margin. The fix is transparent, interchange-plus pricing with a statement a business owner can actually audit.
What to Look for in a Payment Processor for Your Trade
A payment processor for home service businesses should be evaluated on four criteria: contract flexibility, pricing transparency, hardware durability, and integration depth. Most guides focus on the first two, but the last two determine whether the system survives contact with a job site.
Contract flexibility matters because home service revenue is seasonal. Look for month-to-month terms with no early termination fees, and confirm the processor does not impose rolling reserves during slow periods.
Pricing transparency means interchange-plus or flat-rate pricing with no monthly “compliance” or “statement” fees. If a sales rep cannot explain every line item on a sample statement, that is a red flag.
Hardware durability is non-negotiable for field work. A countertop terminal dropped on a concrete basement floor will not survive the season. Look for ruggedized mobile readers with long battery life and cellular fallback when Wi-Fi is unavailable.
Integration depth determines whether payments flow into the existing scheduling and invoicing software or require manual reconciliation. A processor that integrates with the field service management platform eliminates double entry and reduces errors.
Understanding Interchange-Plus vs. Tiered Pricing
Interchange-plus pricing is a billing model where the processor passes through the card network’s interchange fee plus a small fixed markup. Tiered pricing bundles transactions into categories like “qualified” and “non-qualified” at the processor’s discretion.
The practical difference is predictability. With interchange-plus, the markup is constant regardless of card type. With tiered pricing, a rewards card that should cost 2.3% can suddenly be bucketed as “non-qualified” at 3.5%, and the business owner has no way to verify the reclassification. According to guidance from the Federal Trade Commission’s business guidance on payment processing, merchants should demand a full explanation of all fees before signing and should be wary of processors that obscure interchange costs.
Mobile Credit Card Processing for Contractors in the Field
Mobile credit card processing for contractors has evolved from clunky Bluetooth readers to full point-of-sale apps on a standard smartphone. The modern setup pairs a chip-and-tap reader with an app that handles invoicing, inventory, and customer records, all from the same device a technician already carries.
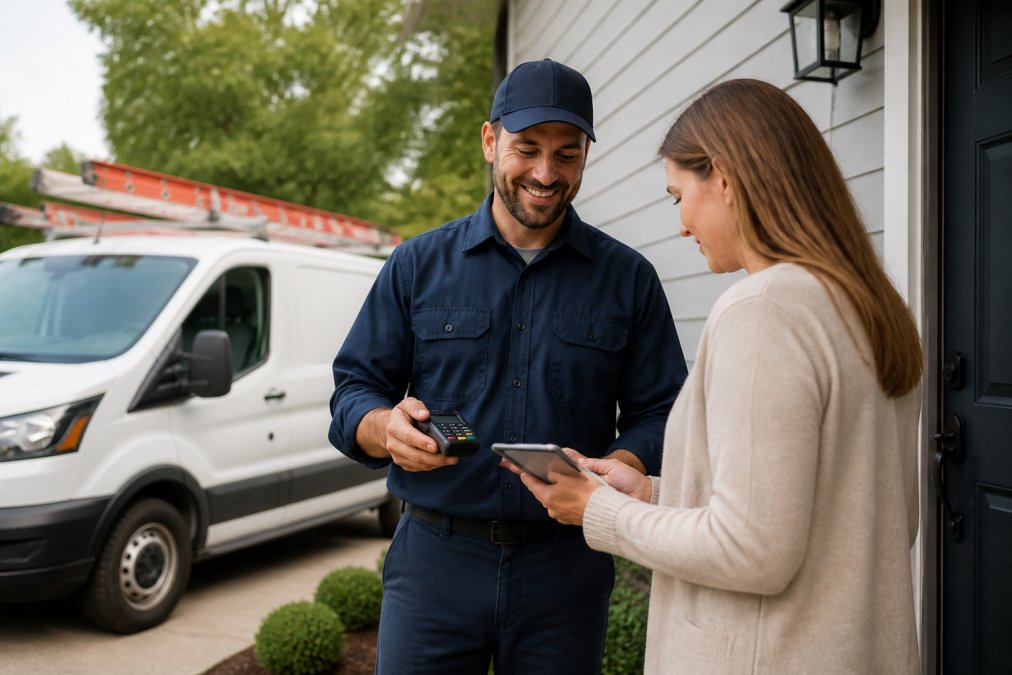
The workflow is straightforward. After completing the work, the technician enters the job details, emails or texts an invoice, and collects payment on the spot. This eliminates the “invoice and pray” model where contractors hope a customer mails a check weeks later. Field collection also reduces accounts receivable aging, which is the leading cause of cash flow problems for small trades businesses.
Battery life and connectivity are the two practical concerns. A reader that dies mid-transaction or an app that requires strong Wi-Fi will fail on a job site. Look for readers with a full-day battery and an app that buffers transactions for offline processing, syncing when the technician returns to cellular coverage.
Recurring Billing Software for Home Services and Maintenance Plans
Recurring billing software for home services turns one-time jobs into predictable monthly revenue. A pest control company that sells quarterly treatments, or an HVAC firm with annual tune-up plans, needs a system that automatically charges customers on schedule without manual intervention.
The core requirement is dunning management, the automated process of retrying failed payments and notifying customers before cancellation. Many home service businesses lose a portion of their recurring revenue simply because a card expired and no one followed up. Good recurring billing software handles this automatically, sending a payment update link via email or text.
Recurring billing software for home services also needs to handle variable amounts. A lawn care contract might bill monthly at a flat rate, but a plumbing maintenance plan could include a one-time service call at a different price. The system should support both subscription-style billing and ad-hoc charges without requiring separate workflows.
PCI Compliance for Mobile Payments: What Technicians Need to Know
PCI compliance for mobile payments is less about the terminal and more about the habits of the person holding it. The Payment Card Industry Data Security Standard applies to any business that accepts card payments, and mobile processing does not exempt a contractor from its requirements. But the official guidance from the PCI Security Standards Council’s guidance on mobile payment acceptance is written for a broad audience. Translating it to the realities of a service van reveals a set of specific, avoidable risks.
The practical risks on a job site are straightforward. A technician who writes down a customer’s card number to “run it later” has just created a potential data breach. A phone left unlocked with the payment app open is an access risk. PCI compliance for mobile payments means the card data never touches the technician’s device in readable form; it goes directly from the reader to the processor through encryption.
The Job Site Scenarios That Create Real Exposure
A common pattern is the “good Samaritan” violation. A customer wants to pay but their card is damaged, or they left it in the house. The technician offers to key in the number manually. That single act converts a secure, encrypted transaction into a manual entry that is both a higher interchange rate and a compliance liability. The card data now exists in the app’s memory, and if the phone is later lost or stolen, that data is potentially recoverable. The fix is to never offer manual entry as a convenience. If a card is present but unreadable, the customer needs a different card or a payment link sent to their phone.
Another scenario is the “parked truck” problem. A technician finishes a job, tosses the phone and reader on the passenger seat, and drives to the next call. If the truck is broken into, the thief now has a phone with a payment app and a card reader. Most payment apps require a PIN or biometric login, but many technicians disable that for speed. Requiring a phone lock screen and an app-level PIN or biometric check is a non-negotiable policy, not a suggestion.
What the Self-Assessment Questionnaire Actually Covers
Most home service businesses fall under SAQ A or SAQ C-VT, depending on how they process. SAQ A applies when card data is fully outsourced to a validated third party, which is the case with most modern mobile readers that use point-to-point encryption. SAQ C-VT applies when a virtual terminal is used on a desktop or laptop. The distinction matters because the questionnaire asks different questions. A technician using a mobile reader with P2PE encryption is not responsible for the same controls as an office manager typing card numbers into a web portal.
The annual Self-Assessment Questionnaire is not a formality. It asks specific questions about whether card data is stored, how it is transmitted, and who has access. A contractor who cannot answer those questions without guessing is not compliant. The processor should provide a compliance portal that tracks SAQ status and deadlines. If the processor does not offer this, that is a red flag. tax software for businesses.
The Verbal Payment Trap
Accepting card numbers verbally over the phone and keying them into an app manually is the fastest way to lose PCI compliance. If a customer wants to pay by phone, use a secure payment link sent via text or email instead of manual entry.
This is the single most common violation in home services. A customer calls to schedule a repair and asks to prepay. The office staff takes the card number over the phone and enters it into the virtual terminal. That data is now in the office’s system, subject to a different and more burdensome set of PCI requirements. The alternative is a payment link, which redirects the customer to a secure page hosted by the processor. The office never touches the card data, and the compliance burden drops dramatically.
A Practical Field Policy for Compliance
A simple field policy covers most exposure. Technicians should be instructed to never write down card numbers, never key in a card manually unless the customer is physically present and the card is readable, and never leave a phone with a payment app unlocked. The reader should be paired to a single phone, and the app should require a PIN or biometric login on every launch. If a phone is lost or stolen, the processor must be notified immediately so the device can be remotely deactivated. These are not theoretical concerns; they are the exact scenarios that lead to data breaches and the fines that follow.
Hidden Fees and How to Audit Your Current Statement
Every payment processor charges interchange, the wholesale cost set by Visa and Mastercard. The fees that quietly drain a home service business are the ones layered on top: monthly gateway fees, PCI compliance fees, statement fees, and “non-qualified” surcharges that appear without explanation.
A statement audit is a 15-minute exercise that pays for itself. Pull the last three months of statements and calculate the effective rate by dividing total fees by total volume. If the effective rate is more than 0.5% above the published interchange-plus markup, hidden fees are the reason.
The most common culprit is the “non-qualified” bucket. Processors that use tiered pricing can reclassify a standard transaction as non-qualified based on factors the merchant never sees, such as the card type or how the data was submitted. The fix is to demand interchange-plus pricing, where the processor’s markup is fixed and the interchange rate is passed through at cost.
Hardware Troubleshooting and Connectivity on the Job Site
Hardware failures always happen at the worst moment, usually in a customer’s basement with a dead zone for cellular service. A basic troubleshooting sequence resolves most issues without a service call. But the most common failures are not random; they follow predictable patterns that a prepared technician can prevent or resolve in under two minutes.
The 90-Second Connectivity Reset
When a reader will not process, the issue is almost always a stale Bluetooth connection or a phone that has silently dropped its data connection. The fastest fix is a full reset sequence, not a single toggle. First, close the payment app completely, not just background it. On an iPhone, swipe up and hold, then swipe the app away. On Android, access the app switcher and swipe it away. Second, toggle Bluetooth off and on. Third, toggle cellular data off and on. Fourth, reopen the app and attempt the transaction again. This sequence clears the most common software-level stalls in under 90 seconds.
If the reader still will not connect, check whether the reader is paired to the correct phone. A common issue is a technician who has two phones, or a crew that shares a reader between two phones. The reader can only maintain one active Bluetooth connection. If the reader was last paired to a different phone, it will not connect to the current one until it is reset. Most readers have a physical button or a specific button combination to force a re-pair. Know that sequence before you need it.
The Cold Weather Battery Problem
Battery problems are the second most common failure, and they are largely preventable. Mobile readers lose charge faster in cold weather, and a reader left in a truck overnight during winter will be dead by morning. The chemistry of lithium-ion batteries is such that cold temperatures increase internal resistance, which makes the battery drain faster and also makes the voltage drop more sharply under load. A reader that shows 40% charge in the office can die mid-transaction in a 30-degree driveway.
The fix is a charging routine, not a reaction. Make it a habit to charge the reader and the phone simultaneously each evening, ideally in a heated space. If the reader is stored in the truck, bring it inside during winter months. A reader that has been exposed to extreme cold should be warmed gradually, not placed on a heater or dashboard, which can damage the battery.
The Dead Zone Reality
Cellular dead zones are a structural reality of home services. Basements with concrete walls, rural properties, and multi-story buildings with thick interior walls all block cellular signal. The payment app cannot process a transaction without a data connection, but the reader can still capture the card data. The question is whether the app buffers the transaction for later transmission.
Most modern mobile payment apps support offline mode, but it is not always enabled by default. Check the app settings and confirm that offline transactions are turned on. When a transaction is processed offline, the card is authorized at the time of the swipe, but the settlement is delayed until the phone reconnects. This means the funds are not guaranteed until the transaction is transmitted. For low-value transactions, this risk is acceptable. For high-value jobs, a technician should be honest with the customer that the payment is pending, or should use a different method.
The Firmware Update Blind Spot
Firmware updates are the most overlooked maintenance task. Reader manufacturers release updates that fix connectivity bugs, improve battery management, and patch security vulnerabilities. A reader that has not been updated in six months may have a known issue that was already fixed. Most readers require the phone to be on Wi-Fi to download the update, which means the update will not happen on a job site. Make it a weekly habit to connect the reader to the phone and check for updates while the phone is on home Wi-Fi. This is a five-minute task that prevents a class of failures that are otherwise mysterious.
The Backup Reader Policy
Keep a spare card reader in the truck, not in the office. A $50 backup reader prevents the most expensive outcome: finishing a job and being unable to collect payment, then waiting weeks for a check that may never arrive.
A backup reader is not a luxury; it is a business continuity tool. The cost of a missed collection is not just the invoice amount; it is the collection time, the accounts receivable aging, and the risk of non-payment. A backup reader that is already paired to the phone and charged can be swapped in during a failure in under a minute. The backup should be tested monthly, not just stored. A reader that sits in a truck for six months may have a dead battery or outdated firmware. Rotate the backup into active use periodically to keep it ready.
The Escalation Path
When a reader fails and the basic reset does not fix it, the technician needs a clear escalation path. The processor’s support line should be available during all working hours, not just 9-to-5. A technician who is stuck at a job site at 6 PM with a dead reader needs a human, not a chatbot. Before the season starts, call the processor’s support line and confirm the hours and the average hold time. A processor that cannot answer a support call in under two minutes during peak evening hours is a liability. The support team should also be able to remotely diagnose a reader issue, which requires the technician to have the reader’s serial number and the phone’s app version available.
Conclusion: Build a Payment Stack That Scales With Your Crew
The payment stack that works for a two-person operation will not survive a ten-truck fleet. As a crew grows, the owner needs consolidated reporting across technicians, per-employee permissions, and a processor that does not renegotiate rates when monthly volume increases. Payment processing for home service businesses is not a one-time purchase; it is an ongoing relationship that should improve as the business scales.
Many home service owners accept high fees and poor support because switching feels disruptive. It does not have to be. A processor that handles the migration, offers transparent interchange-plus pricing, and provides support that answers when a technician calls at 7 PM from a job site changes the economics of the entire operation. The team at Merchant Card Advisors has built its practice around exactly this kind of consultative transition for trades businesses, with fair pricing and no rate bumps.
Get started with Merchant Card Advisors and build a payment stack that collects faster, costs less, and scales with your business.
Frequently Asked Questions
What features should home service businesses look for in a payment processor?
Prioritize transparent interchange-plus pricing, no long-term contracts, and a provider that specializes in your industry. Look for mobile payment options for technicians, recurring billing for maintenance plans, and clear monthly statements. 24/7 live support matters when you process payments after hours. Confirm the processor offers PCI-compliant tools and works with your existing software to avoid manual reconciliation.
How do mobile payment solutions benefit field technicians?
Mobile credit card processing for contractors lets technicians collect payment immediately after completing a job. This reduces the risk of late or missed invoices and improves cash flow. Technicians can email receipts on the spot, which builds trust with customers. Many mobile solutions also support invoicing and payment links for follow-up work, creating a smoother checkout flow without requiring a physical office.
Are there specific payment processing risks for home service providers?
The main risks involve entering card details manually, which increases the chance of errors and potential disputes. Technicians working alone can also be targets for fraud. Using EMV chip readers and encrypted mobile apps reduces these risks. PCI compliance for mobile payments requires using secure networks rather than public Wi-Fi. A processor that monitors transactions for unusual activity adds another layer of protection.
How can integrated payment processing improve cash flow for service businesses?
Integrated payment processing connects your payment system with your scheduling, invoicing, and accounting software. When a job is marked complete, the system automatically charges the customer on file and updates your books. This removes the delay between finishing a job and getting paid. It also supports recurring billing software for home services, ensuring predictable revenue from maintenance contracts without manual invoicing.

