

Table of Contents
- What Are Hidden Fees in Merchant Statements?
- Common Types of Hidden Processing Fees
- How to Read a Merchant Statement and Spot Hidden Fees
- Interchange-Plus vs. Tiered Pricing: Which Costs Less?
- How to Lower Credit Card Processing Fees
- Merchant Statement Analysis Template and Audit Tools
- Taking Action: Contract Review and Legal Recourse
- Frequently Asked Questions
Last Updated: October 2, 2026
What Are Hidden Fees in Merchant Statements?
Hidden fees merchant statements are charges that appear beyond the advertised processing rate. A business owner might negotiate a rate of 2.9% plus interchange, only to discover the actual cost reaches 4% or higher once authorization fees, gateway charges, batch fees, and compliance assessments are factored in. These additional costs accumulate quietly across monthly statements, eroding margins without clear visibility. (Source: the Federal Trade Commission’s guidance on deceptive pricing)
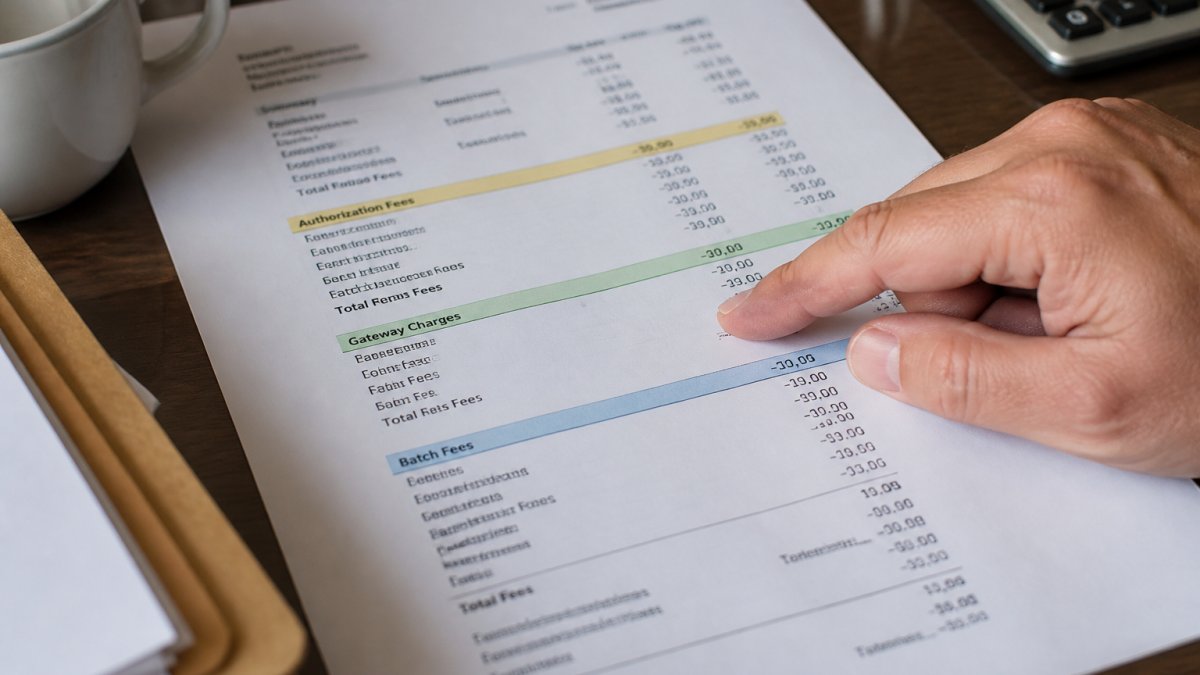
Payment processors layer on additional charges beyond interchange to cover infrastructure, fraud prevention, and risk management. The real problem is that these fees are often buried in statement line items without clear explanation of what triggered them or how they’re calculated.
A 2.9% quote sounds competitive until the merchant realizes it excludes authorization fees ($0.10 per transaction), batch header fees, gateway passthrough charges, and PCI penalties. The cumulative effect transforms an apparently reasonable rate into a significant cost burden.
Why These Fees Exist and How They Add Up
Payment processors operate in a multi-layered ecosystem: the acquiring bank handles settlement, the processor provides technology infrastructure, and payment networks assess fees on every transaction.
Common fee categories include assessment fees from card networks, non-qualified transaction markups, monthly minimums, authorization fees per transaction, gateway passthrough fees, and PCI compliance fees for security standard violations.
Merchants often focus on the headline rate and overlook itemized charges. A 0.5% processor markup on 10,000 monthly transactions translates to hundreds of dollars in additional cost.
Common Types of Hidden Processing Fees
Authorization and Gateway Passthrough Charges
Authorization fees charge merchants for every transaction attempt. A processor charging $0.10 per authorization on 5,000 monthly transactions adds $500 in fees alone.
Gateway passthrough fees cover payment gateway infrastructure costs, typically $25 to $50 monthly for custom integrations.
Examine statements line by line for entries labeled “authorization,” “gateway,” or “passthrough.” Cross-reference against the contract to confirm disclosure. Many merchants discover these fees were never explicitly mentioned during sales.
Non-Qualified Transaction Markups
Qualified transactions meet specific criteria: card present, cardholder verified, and settlement within defined parameters. Non-qualified transactions include card-not-present scenarios, missing address verification, or keyed-in entries.
Processors apply 1-2% higher markup rates to non-qualified transactions.
Recurring billing, phone orders, and online purchases often trigger non-qualified rates. A dental practice processing phone payments faces non-qualified rates on every transaction, compounding across hundreds of monthly transactions.
PCI Compliance and Batch Header Fees
PCI compliance fees appear when merchants fail to maintain required security standards. Non-compliance triggers monthly penalties, typically $25 to $100, depending on the processor and violation severity.
Batch header fees range from $0.50 to $1.00 per batch. A business settling multiple times daily accumulates $50 to $100 in batch fees monthly.
These fees often go unnoticed because they’re small individually. A $1.00 batch fee multiplied across 30 batches monthly totals $30, or $360 annually, potentially eliminated through contract negotiation.
How to Read a Merchant Statement and Spot Hidden Fees
Understanding Statement Line Items
A merchant statement contains a summary section showing total processing volume, transaction count, and aggregated fees, plus a detailed section breaking down individual fees by category. Learning to read this document identifies hidden costs.
Focus on total sales volume, transaction count, effective rate (total fees ÷ total volume), and itemized fees. The effective rate is the true processing cost. If it exceeds the quoted rate by more than 0.5%, investigate.
Common statement line items include interchange fees, assessment fees, processing fees, authorization fees, gateway fees, batch fees, statement fees, and PCI compliance fees. Each should map back to the contract. Charges without corresponding contract clauses signal predatory pricing.
Red Flags That Signal Predatory Pricing
Predatory pricing reveals itself when the effective rate significantly exceeds the quoted rate.
Unclear line items like “misc fee,” “service charge,” or “other” signal cost obscuring.
Monthly minimums of $200 to $500 devastate early-stage and seasonal businesses, punishing low-volume months and creating inflexible cost structures.
Early termination fees locking merchants into 24-36 month contracts with $300-$500 exit costs prevent switching.
Processors refusing to provide detailed, itemized statements are hiding something.
Interchange-Plus vs. Tiered Pricing: Which Costs Less?
Interchange-plus pricing passes through the actual interchange rate, then adds the processor’s markup. A merchant might pay 1.51% (Visa interchange) plus 0.35% (processor markup), totaling 1.86%. The advantage is transparency.
Tiered pricing bundles transactions into qualified (1.99%), mid-qualified (2.99%), and non-qualified (3.99%) tiers. The advantage is simplicity; the disadvantage is opacity, processors can shift transactions into higher tiers, inflating costs without merchant knowledge.
Interchange-plus typically costs less for high-volume merchants with qualified transactions, preventing hidden markups. Tiered pricing benefits low-volume merchants but creates opportunities for processors to increase rates through transaction categorization.
For hard-to-place industries or high chargeback rates, interchange-plus provides better cost control with fixed processor markup.
How to Lower Credit Card Processing Fees
Negotiating Your Merchant Service Agreement
Negotiating fees requires understanding what’s negotiable and what isn’t. Interchange rates are set by card networks and cannot be negotiated.
Start by requesting a detailed cost breakdown. Ask the processor to itemize every charge and explain what it covers.
Use competitive quotes. Obtain proposals from multiple processors and use them as negotiating tools.
Document everything in writing. Verbal promises of rate reductions or fee waivers are worthless. Insist that any negotiated terms be reflected in the updated contract.
Reducing Non-Qualified Transactions
Non-qualified transactions carry higher rates, so reducing them directly lowers overall costs. For card-not-present businesses, this is challenging, but several strategies help.
For subscription and recurring billing businesses, setting up card-on-file transactions often qualifies at lower rates than one-time card-not-present transactions.
For retail and service businesses, encouraging card-present transactions reduces non-qualified rates.
Monitoring transaction qualification on the monthly statement reveals which transaction types are being classified as non-qualified.
Merchant Statement Analysis Template and Audit Tools
Building Your Own Statement Audit Process
A hidden fees merchant statements audit process involves systematically reviewing each line item and verifying it against the contract.
Calculate the effective rate monthly. Divide total fees by total processing volume to determine the true cost of processing. Track this metric over time to identify trends.
Document all discrepancies. If a charge appears without a contract reference, flag it. If an amount exceeds the contract terms, calculate the variance. Accumulate these discrepancies over three to six months.
What to Track and Calculate
| Metric | Calculation | Purpose |
|---|---|---|
| Effective Rate | Total fees ÷ Total volume | True processing cost |
| Non-Qualified Percentage | Non-qualified transactions ÷ Total transactions | Identifies downgrade risk |
| Cost per Transaction | Total fees ÷ Transaction count | Tracks per-unit economics |
| Monthly Variance | Actual fees – Expected fees | Spots unauthorized increases |
| Markup vs. Interchange | Processor markup ÷ Interchange rate | Measures processor profitability |
Track the percentage of transactions classified as non-qualified each month. A sudden increase signals a change in processor behavior or a shift in transaction types.
Calculate the cost per transaction by dividing total fees by transaction count.
Monitor the ratio of processor markup to interchange costs. If interchange represents 60% of total fees and processor markup represents 40%, the processor is capturing significant value.
Taking Action: Contract Review and Legal Recourse
A merchant statement audit often reveals that the current processor is charging more than the contract allows. In these cases, formal dispute resolution is appropriate.
If the processor refuses to correct unauthorized charges, the next step is legal action. Many merchant service agreements include arbitration clauses, requiring disputes to be resolved through arbitration rather than court litigation. Review the contract to understand the dispute resolution process.
For merchants in hard-to-place industries or with high chargeback rates, switching processors can be challenging. However, persistent predatory pricing justifies the effort.
Documentation is critical. Maintain copies of all contracts, statements, and correspondence with the processor. This documentation supports any dispute claim and demonstrates that the merchant acted in good faith to resolve the issue.
Frequently Asked Questions
What are the most common hidden fees that appear on merchant statements?
Common hidden fees include gateway passthrough charges, batch header fees, PCI compliance fees, authorization fees, and non-qualified transaction markups. These often appear as separate line items on your statement and can add 0.5% to 2% to your overall processing costs. Many small business owners miss these charges because they focus only on the advertised discount rate rather than examining every line item on their merchant statement.
How much can I realistically save by switching to interchange-plus pricing?
Savings depend on your transaction volume and mix, but businesses often save 0.5% to 1.5% annually by switching from tiered pricing to interchange-plus. With interchange-plus pricing, you pay the actual interchange rate set by card networks plus a transparent processor markup, eliminating the incentive for processors to push transactions into higher-cost tiers. To calculate your potential savings, request a statement analysis from your current processor and compare the effective rate against an interchange-plus quote.
What does it mean if my effective rate is higher than my quoted rate?
Your effective rate (total fees divided by total processing volume) exceeds your quoted rate when hidden fees, non-qualified markups, and monthly minimums are added to your base discount rate. For example, a 2.9% quoted rate can become 3.8% to 4.2% effective when all fees are included. This gap signals either a poor pricing structure or that your transaction mix contains many non-qualified transactions that trigger higher markups.
How do I know if my contract terms are unfair or predatory?
Red flags include early termination fees exceeding 3 months of processing volume, monthly minimums with no cap on how long they apply, automatic rate increases at contract renewal without notice, and vague language around what qualifies as a ‘non-qualified’ transaction. Request a full statement audit and comparison from a consultative payment processor. If your current provider cannot clearly explain every fee or resists providing detailed statements, that’s a sign to seek a second opinion on your contract terms.
Hidden fees in merchant statements erode profitability and create uncertainty around true processing costs. Merchants who take time to audit statements, understand fee structures, and negotiate transparent pricing regain control of a significant operating expense. Merchant Card Advisors provides consultative support to help businesses identify hidden costs, negotiate better terms, and implement ongoing auditing processes that ensure fair pricing year after year.

